PMC Bank, 2019
In September 2019 the RBI placed Punjab and Maharashtra Co-operative (PMC) Bank, a large urban co-operative bank based in Mumbai, under restrictions after serious problems came to light in its loans. Overnight, depositors could withdraw only ₹1,000 per account.
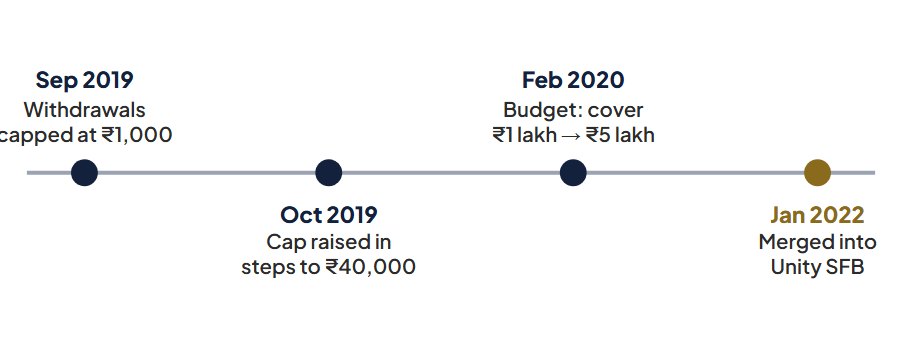
The limit was raised in steps: ₹10,000 on 26 September, ₹25,000 and then ₹40,000 in October 2019, and ₹1 lakh by June 2020. In the Budget of 1 February 2020 the government raised deposit insurance from ₹1 lakh to ₹5 lakh per depositor. In January 2022 PMC Bank was merged into Unity Small Finance Bank under an RBI scheme that paid depositors their full balances in stages, some over as long as ten years.
What the story teaches
Many PMC depositors were retired people and small businesses who had chosen the bank for its convenient branches and slightly higher rates. Their money was not lost in the end, but for months and in some cases years it was out of reach, including money meant for medical bills and daily expenses.
- Spread large sums across banks. Keep each depositor’s money at one bank within the insured limit, or close to it, where you can.
- Don’t keep all of parents’ money in one place. Retired people can least afford to wait for access.
- Higher rates have a reason. A bank paying noticeably more than others may be taking more risk.
- Keep a cushion elsewhere. Some money in a second bank or a liquid fund means a freeze at one bank isn’t a crisis.
Chapter 2: Bank FDs and deposit insurance
Bank deposits are insured up to a limit per depositor per bank. Spread large sums so that the insured part covers most of your money, and choose banks with care.
- Explain what deposit insurance covers and what it doesn’t
- Spread deposits to stay within insured limits
- Choose FD types to suit income, access and tax
This article is adapted from the book. Examples marked “Example” use invented names and numbers; company stories are based on public sources listed in the book. Education only: not investment, tax or legal advice.